Property investment finance, structured for what comes next.

Whether you are buying your first investment property or adding to your portfolio, your lending decision should support more than one purchase.

MortgageDesign considers your equity, borrowing position, cash flow, lender choice and loan structure together, so your finance is designed around what you want to achieve now and where you want to go next.

How much equity could you use?

For many Property Investors, the next purchase starts with understanding the equity in a property you already own.

Available equity is only one part of the picture. How much you can use also depends on lender policy, property values, existing lending, income, expenses and overall borrowing capacity.

OUR REVIEW CAN HELP YOU CLARIFY:
Lending

The aim is to understand what equity can support without weakening the wider lending position.

Three-step-equity-pathway-infographic-investment

What can you realistically borrow next?

Property value alone does not determine whether another purchase will be approved. Lenders also assess income, existing debt, living costs, rental income, loan commitments and their own credit policy.

They also apply Reserve Bank lending restrictions, including deposit and debt-to-income requirements, which can limit how much an investor may be able to borrow even when there is strong equity in the portfolio.

Rental income is another important factor. Most lenders do not use the full rental amount when assessing affordability, so the income they recognise for servicing purposes may be lower than the actual rent received.

MORTGAGEDESIGN REVIEWS THE WIDER POSITION, INCLUDING
STRATEGIC MORTGAGE ADVICE

Current lending and repayment commitments

STRATEGIC MORTGAGE ADVICE

Income and recognised rental income

STRATEGIC MORTGAGE ADVICE

Existing property values and usable equity

STRATEGIC MORTGAGE ADVICE

Debt and other credit commitments

STRATEGIC MORTGAGE ADVICE

Deposit and debt-to-income requirements

STRATEGIC MORTGAGE ADVICE

The proposed investment and likely loan amount

STRATEGIC MORTGAGE ADVICE

How different lender policies may affect the application

This gives you a more realistic view of the next step before you commit to a property.

Lenders Assess Your Investment Profile

Your loan structure can shape your portfolio.

An investment strategy starts with what you want to buy, why it fits your goals and how it supports the wider portfolio. 

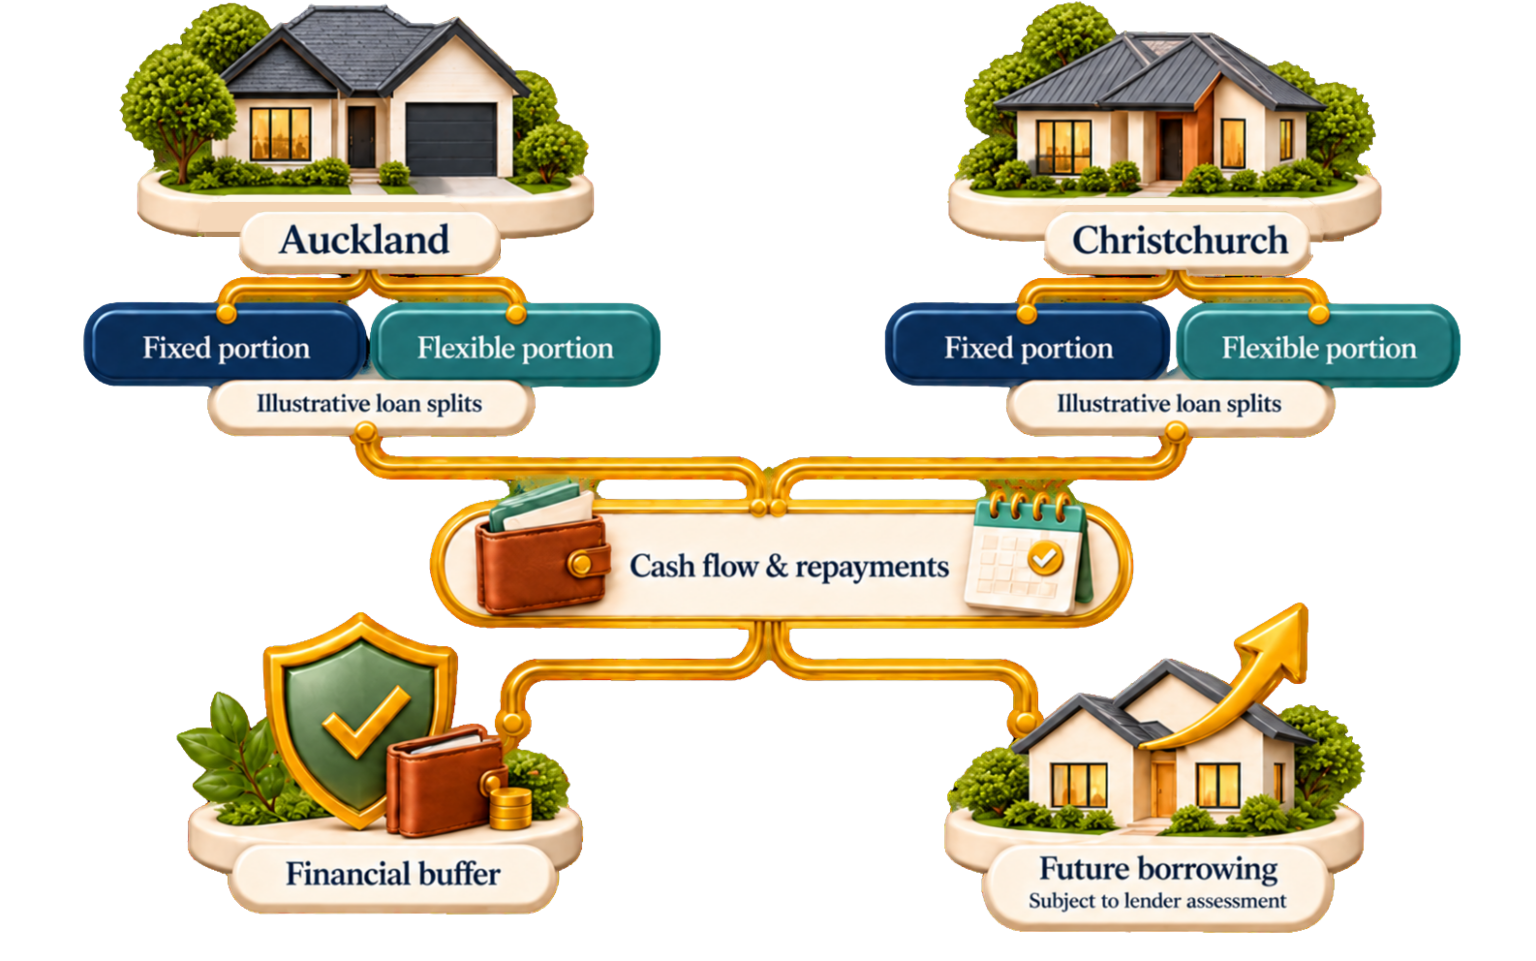
Once the property decision is made, the lending still matters. Getting the loan approved is only one part of it. How the lending is structured can affect your cash flow, flexibility and ability to borrow again later.

Your loan structure can shape your portfolio.

A structure review may consider:

lending-property-icon

How much lending is fixed and for how long

Loan

Whether different portions of the mortgage should have different fixed terms

Credit Icon

Whether floating or revolving credit has a useful role

Repayment

The repayment approach and ability to make extra repayments

Cash flow

Cash flow and the need for a financial buffer

current structure

How the current structure affects future borrowing or another property purchase

Ready to see what your equity could support?

If you are considering your first investment property or planning the next purchase in an existing portfolio, start by understanding what your current position may allow.MortgageDesign can review your equity, borrowing capacity, lender options and loan structure, then recommend the most suitable next step.

One lender is not always the whole picture.

The lender that helped with your first property may still be suitable for the next one, but it should not be assumed automatically.
Different lenders can have different approaches to servicing, rental income, property type, security and overall portfolio exposure.
MortgageDesign compares suitable lender options and looks at the portfolio as a whole before recommending where the next lending may fit.

The recommendation may be to stay with the current lender. It may also be to consider a different lending pathway.

Connected lender comparison overview- investmetn

Advice for different stages of property investment.

The way the loan is funded depends on the type of build and the lender. Two common pathways are a turn-key purchase and a construction loan with progressive drawdowns. 

real-estate-investment

FIRST INVESTMENT PROPERTY

Understand usable equity, realistic borrowing capacity, deposit requirements, lender options and how the first investment loan should be structured.
GROWING AN EXISTING PORTFOLIO

GROWING AN EXISTING PORTFOLIO

Review portfolio equity, cash flow, lender exposure, existing structures and how the next purchase may affect future borrowing.

How mortgagedesign approaches investment lending?

Understand

Understand

Analyze your current portfolio, financial position and what you want the next investment to achieve.

Design

Assess

Review your equity, borrowing capacity, cash flow, existing lending and likely constraints.

Compare

Structure

Design the lending around your purchase and future plans.

Execute

Compare

Assess suitable lender options and explain the differences clearly.

Review

Execute and Review

Manage the lending process and review the structure as the portfolio and the market change.

Frequently asked questions.

Often, yes. What may be available depends on the property values, existing lending, borrowing capacity and lender requirements. A review can help determine what is realistic.

Investors generally need a larger deposit than owner-occupiers under Reserve Bank lending rules, although some exemptions apply, such as for new builds. Your deposit can come from cash, equity or a mix of both. We'll check the current rules against your situation.

Your borrowing capacity depends on more than the deposit. Lenders assess income, rental income, existing debts, expenses, current lending and their own servicing policy.

Often there are different considerations around cash flow, repayments, security and future borrowing. The structure should be designed around the wider portfolio rather than treated as an isolated loan.

Yes absolutely! Existing portfolios often require a broader review of equity, lender exposure, cash flow, loan structure and future borrowing before another purchase is considered.

MortgageDesign provides mortgage and lending advice, not tax advice. Property investment can have tax and ownership implications, so those decisions should be discussed with your accountant, tax adviser or lawyer. Where appropriate, we can work alongside your professional advisers so the lending structure is considered in the context of the wider strategy.

If your home is used as security for investment lending, the properties and loans can become linked. That can affect your flexibility if you later want to sell, refinance or move lending. In some cases, lending can be structured so properties remain more separate. MortgageDesign can explain the different security options, the trade-offs and how they may affect future borrowing before you decide.