Your first home might be closer than you think. The first step is understanding what you can afford, how much you may be able to borrow and what needs to happen before you start making offers.
MortgageDesign helps you understand the numbers, compare suitable lender options and structure the lending around your budget, cash flow and plans beyond settlement.

A realistic borrowing range based on your income, expenses, deposit, debts and lender requirements.
How your deposit affects your options, including pathways that may be available if you have less than 20%.
Whether you’re likely to be eligible to use KiwiSaver towards a first-home purchase and what needs to happen before settlement.
When pre-approval helps, how long it lasts and what lenders will need from you.
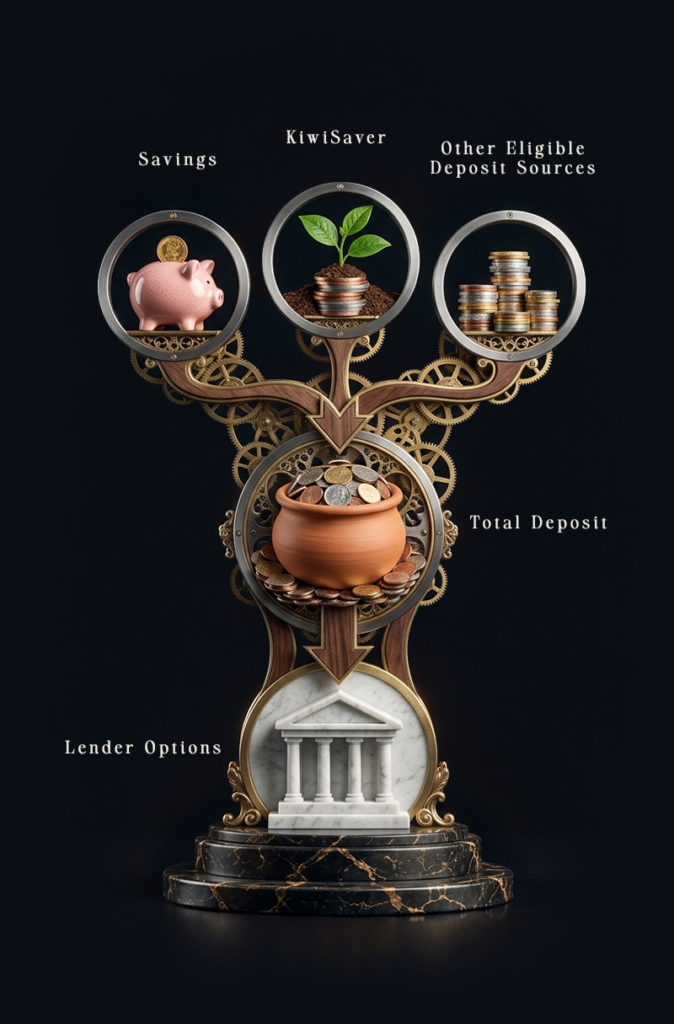
Your deposit is not just a number. It can influence which lenders and lending pathways are available. We’ll look at the deposit you have, show you how it affects your lender options and explain what needs to be in place before you apply.


Different lenders can assess the same borrower differently. MortgageDesign compares suitable lender options and explains the reasoning behind the recommendation rather than sending the application to a lender simply because it is familiar.
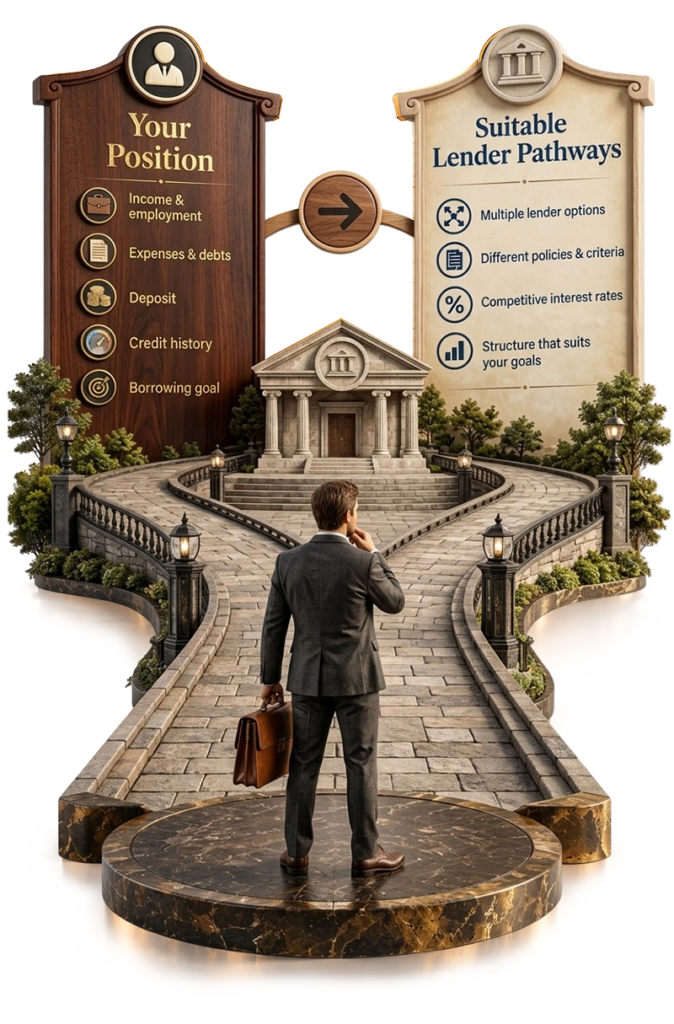
Buying your first home is a significant decision. Understanding what you can afford, how much you may be able to borrow can give you greater confidence before you make your move.


Understand
We talk through your income, deposit, commitments, property goals and what you want your loans to achieve.
Prepare
We identify what information is needed and strengthen your application before it goes to a lender.
Compare
We assess suitable lender options, policy fit and the structure that may work best for your circumstances.
Secure
We help manage the pre-approval and lending application, explain conditions and keep you updated as the application progresses.
Settle and Review
We help guide your lending through to settlement and review your structure annually as rates, goals and circumstances change.
How much you can borrow can vary based on income, expenses, debts, deposit, the lender's policy, and the property itself. A review can give you a more realistic range before you start making offers.
If you meet the eligibility rules, you may be able to use most of your KiwiSaver savings toward your first home. Your KiwiSaver provider confirms eligibility and processes the withdrawal.
No. Pre-approval is usually subject to conditions, and the lender may still need to approve the property and final lending details before the loan becomes unconditional.
Self-employment, variable income, bonuses, commission or other less-standard income can affect how lenders assess an application. Different lenders may treat the same income differently, so lender choice can matter.
Our Service is free in most cases. We are usually paid by the lender once your loan settles, allowing you to receive professional guidance without additional financial pressure.
Not necessarily. The options available can differ depending on how much deposit you have, your financial position and lender criteria. We can show you which options may be worth exploring rather than assuming a 20% deposit is the only pathway.
Ideally before you are ready to make an offer. Understanding your borrowing position, deposit and likely lender requirements early can help you search with more confidence and avoid preventable delays later.
Yes. Family can help with a gifted deposit. Each option has different implications for everyone involved, and lenders have rules on how gifts are documented. We'll explain how each works before anyone commits.