Could refinancing put you in a better position?

Your mortgage may have suited you when it was first arranged, but rates, repayments, income, equity and future plans can change.
MortgageDesign reviews your current lending to see whether refinancing, restructuring or refixing could improve your overall position – or whether staying where you are makes more sense.

Could you get a better overall deal?

For most homeowners, the first question is simple: would changing the mortgage leave me financially better off?

A better deal is not just the lowest advertised rate. A refinance review should consider the full financial effect of moving.

A smarter path to finance

MortgageDesign compares suitable options and looks at the overall lending position before recommending whether a change is worthwhile.

Cashback can be a useful part of the comparison.

Cashback can be a meaningful reason to consider switching lenders, particularly on larger loan balances. It should still be considered alongside the interest rate, repayments, switching costs, loan terms, and any cashback conditions or clawback period.

MortgageDesign can compare suitable lending options and explain how any cashback or incentive fits into the overall refinance decision.

Could you use more of your equity?

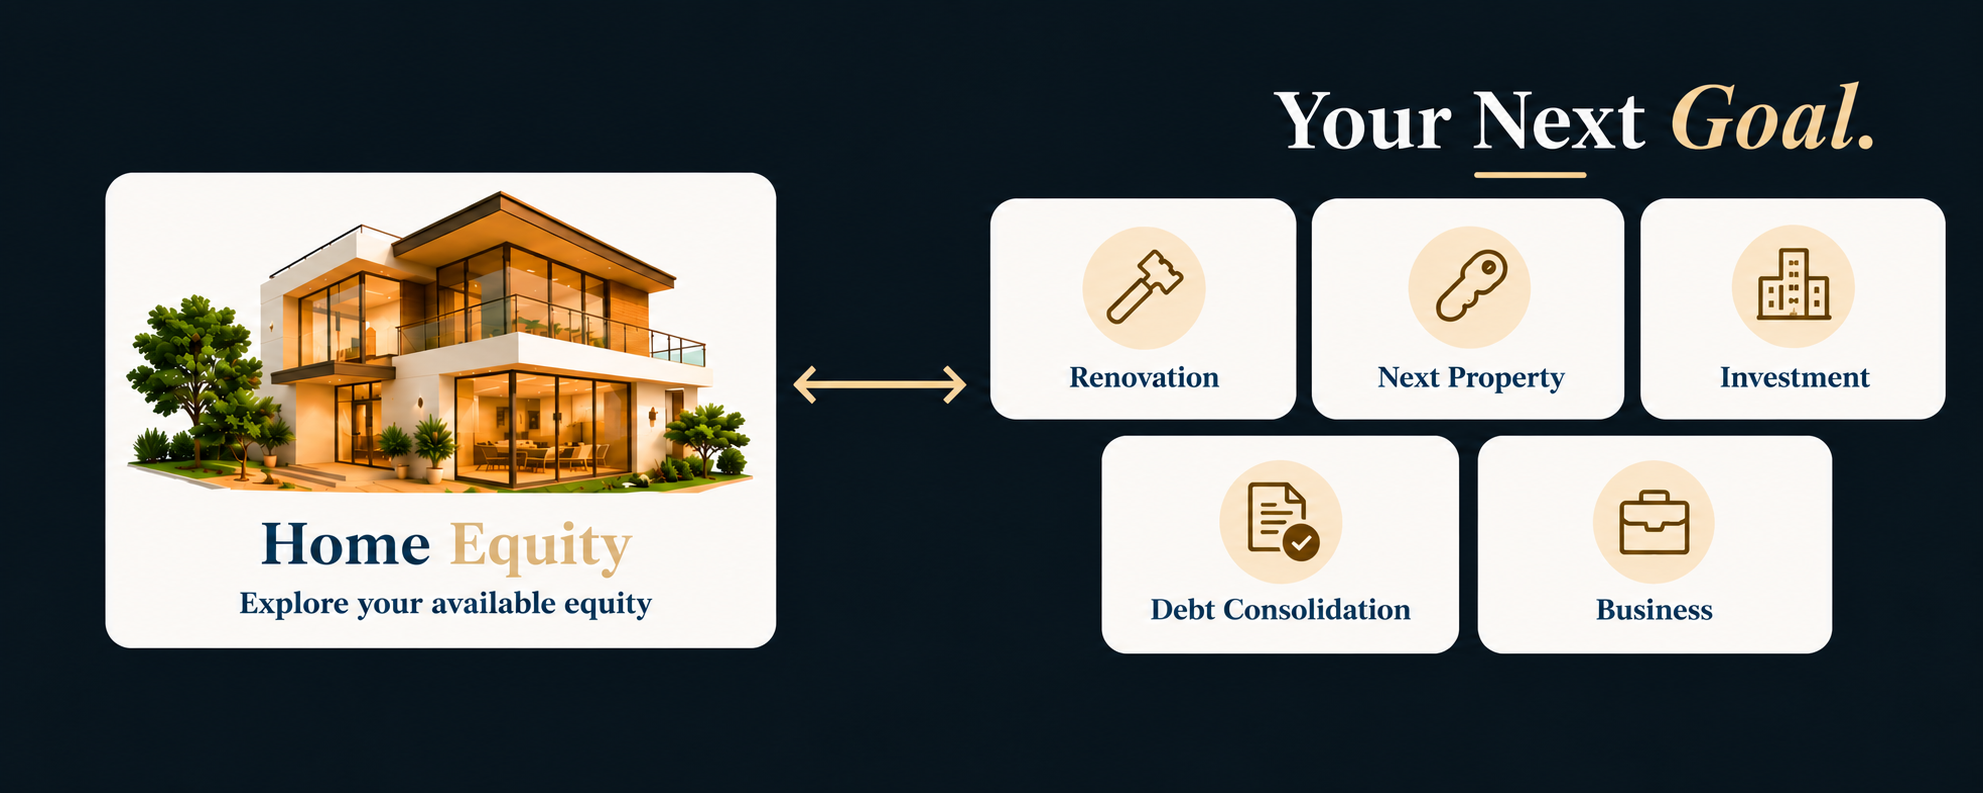
Not every refinance enquiry is simply about getting a lower rate or changing banks. Some homeowners want to understand whether the equity in their property could help fund the next step. Depending on your position and lender requirements, that could include:

Home Equity - Your Next Goal

MortgageDesign can review your existing lending, available equity, borrowing position and suitable lender options before explaining what may be achievable.

Is your loan structure still working for you?

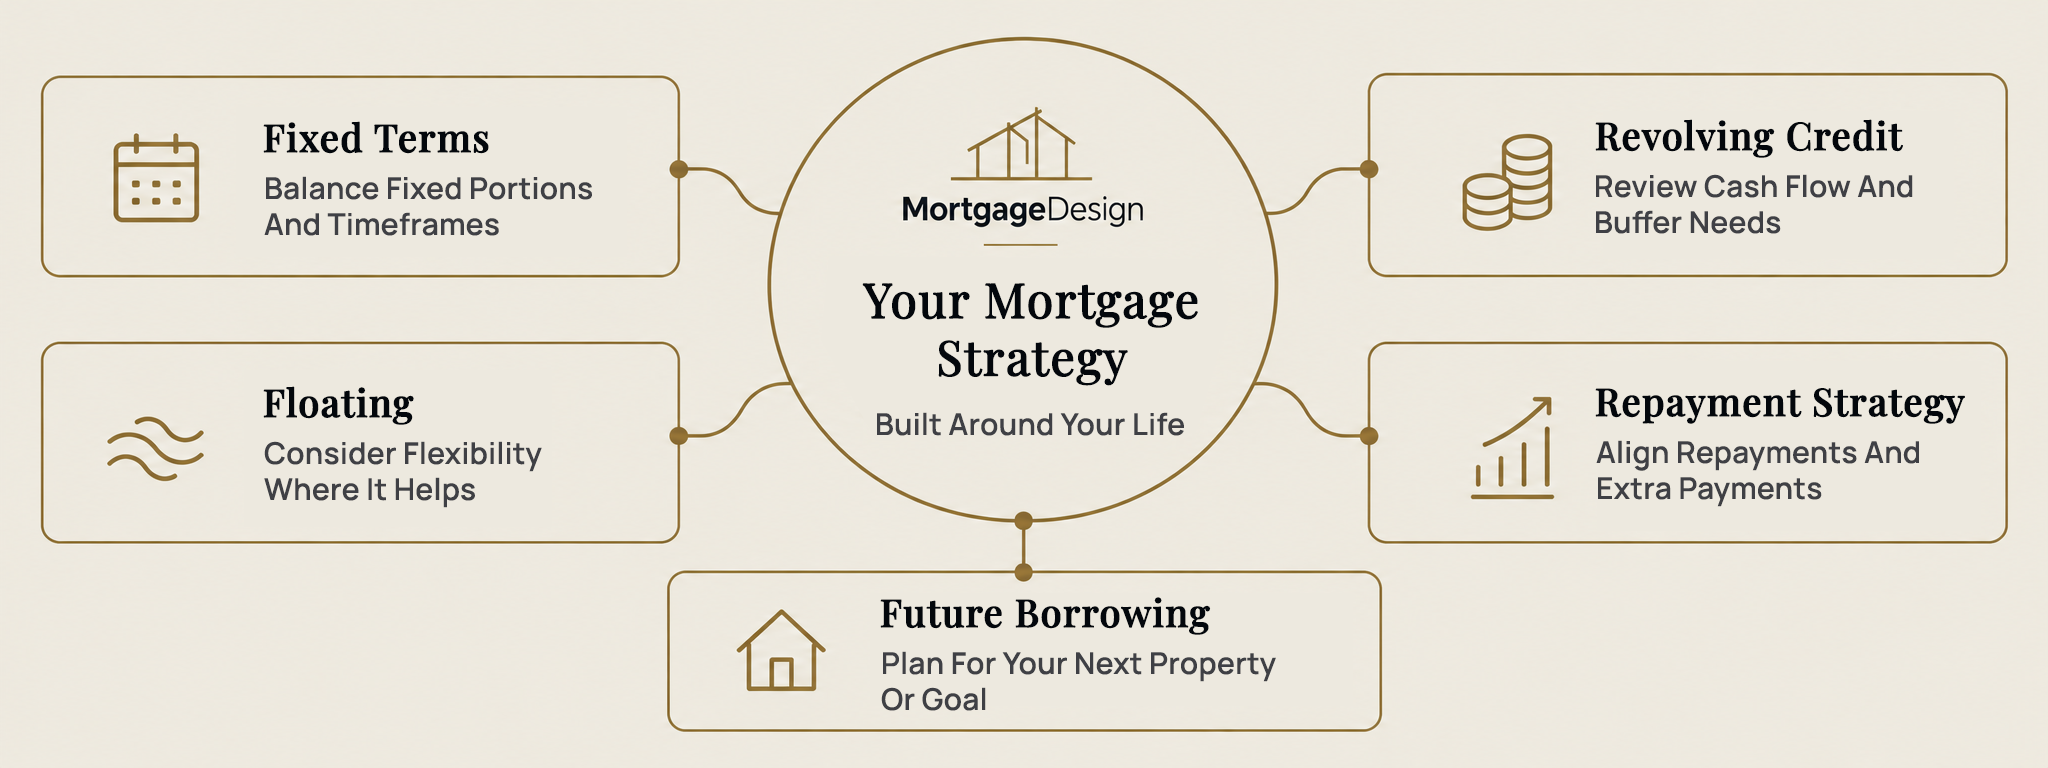
This is one of the most important parts of a mortgage review and a key part of how MortgageDesign approaches lending.Even if the interest rate looks competitive, the way the mortgage is structured can affect day-to-day cash flow, repayment flexibility, how quickly debt is reduced and what may be possible later. A structure review may look at:

Cream-Mortgage-Strategy-Blueprint

Find out whether refinancing makes sense for you.

If you are wondering whether you could get a better overall deal, access equity or improve the way your mortgage is structured, start with a review. MortgageDesign can assess your current position, explain the available pathways and help you decide whether refinancing is worth pursuing now.

Refix, restructure or refinance?

A review does not automatically mean changing lenders.

REFIX

REFIX

Stay with the current lender and choose a new fixed period.
refine

RESTRUCTURE

Change how the lending is arranged - loan splits, repayment approach or the mix of fixed, floating and revolving credit where suitable.
property

REFINANCE

Change the existing lending arrangement, which may include moving to another lender when the overall benefit supports the move.
How mortgagedesign reviews your lending?

Understand

Understand

Review your current mortgage, financial position and what has changed.

Design

Define the goal

Clarify whether the priority is savings, equity, flexibility, another property or a better overall structure.

Compare

Review

Assess the current lender, structure, repayments, equity and relevant switching costs.

Execute

Compare

Where appropriate, compare suitable lender and structure options.

Review

Recommend

Explain whether refinancing, restructuring, refixing or staying where you are is the most suitable next step.

Frequently asked questions.

There is documentation and coordination involved, but you do not have to manage the process alone. MortgageDesign can explain what is required, compare suitable options, prepare the application and help coordinate the lending process through to settlement.

Not always. The costs of moving, your current loan structure, lender terms and future plans all matter. The purpose of a review is to work out whether refinancing makes sense now, whether restructuring or refixing is more suitable, or whether staying with the current lender is the better option.

Possibly, but it depends on your current circumstances and the lender's policy. A review can be particularly useful if you are self-employed, your income or employment has changed, you have new debts or credit commitments, you need higher lending, or your income or existing structure is more complex. Different lenders may assess the same situation differently.

No. The overall result depends on the rate, repayments, switching costs, incentives, loan terms and any relevant cashback conditions or clawback period.

No. Refixing generally means choosing a new fixed period with the current lender. Refinancing involves changing the lending arrangement and may include moving to another lender.

No. A mortgage review may identify suitable options with your current lender as well as alternatives elsewhere.